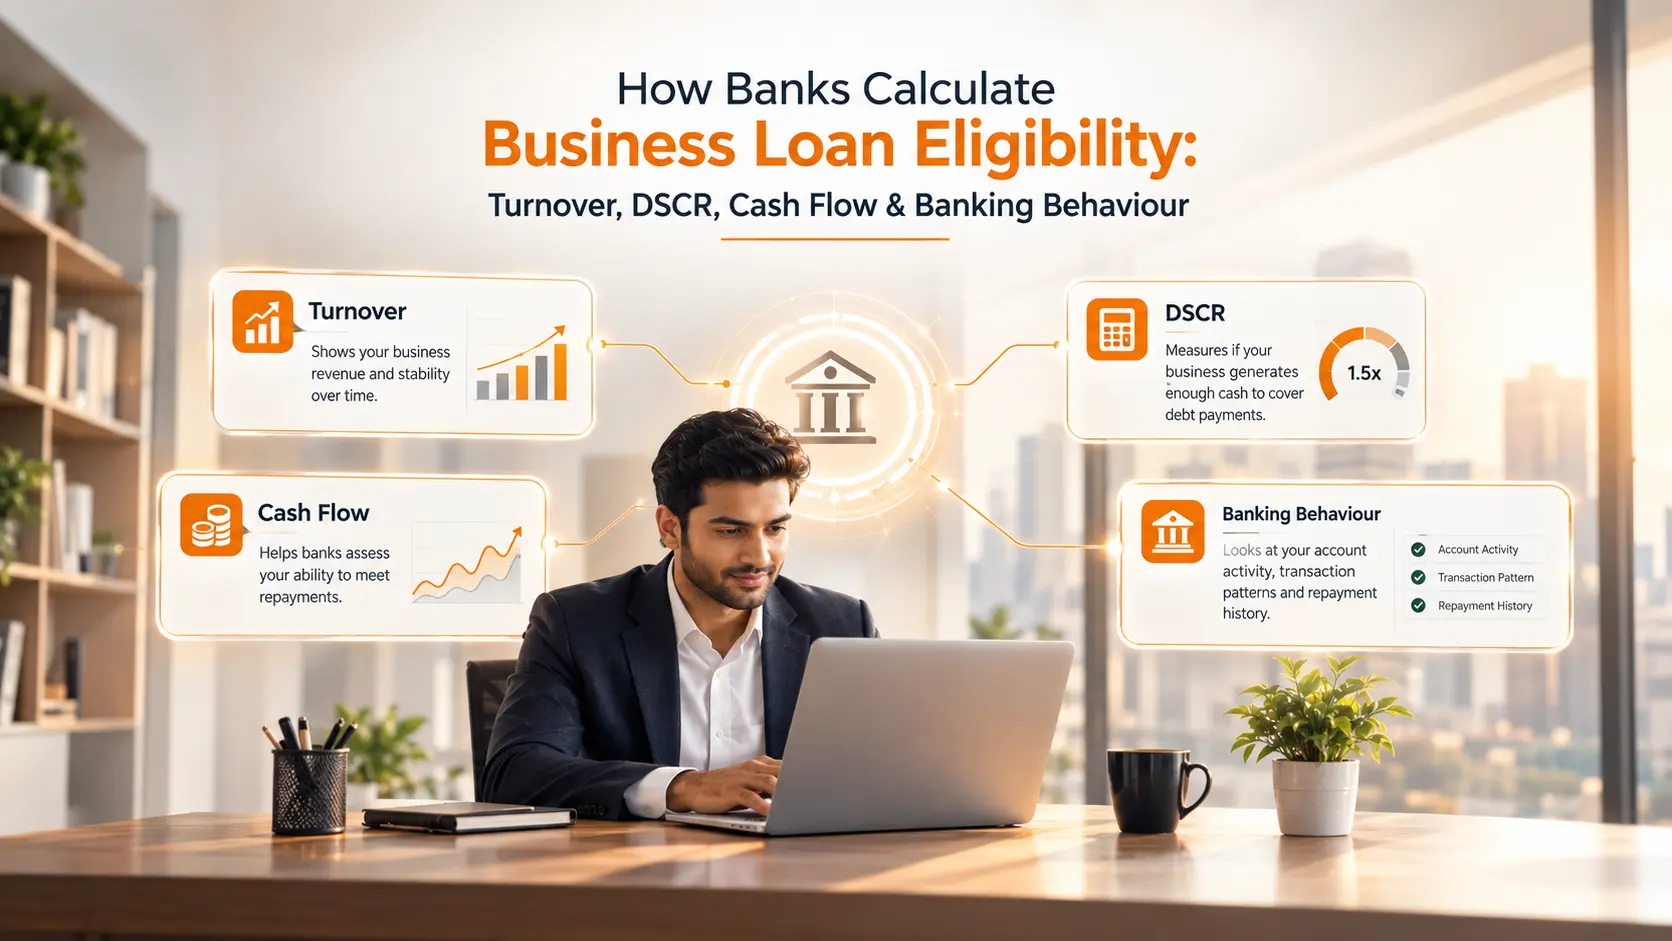
A business can post a healthy turnover and still get turned down for financing, which confuses a lot of owners the first time it happens. The reason usually comes down to a single ratio that rarely gets discussed outside a credit department: how much cash the business actually generates against how much debt it is being asked to service.
That number matters more to a lender than the size of the balance sheet, and understanding how it is built makes the whole underwriting process a lot less mysterious.
Revenue Doesn’t Tell a Lender Whether a Business Can Repay
Turnover measures activity, not capacity to repay. A company can bill several crore worth of business a year and still run so thin on margin, or carry so much existing debt, that it cannot comfortably absorb another loan installment.
Here’s what a lender generally wants to know: is there enough cash left over to cover the principal and interest coming due after the business pays its operating costs?
That question is answered by the debt service coverage ratio (DSCR). It sits closer to the center of an SME loan decision than almost any other single figure.
How Is the Ratio Actually Calculated?
The calculation itself is not complicated, even if the inputs take some digging to get right. DSCR is generally worked out as net operating income divided by total debt service for the same period.
Net operating income is usually built from profit after tax, with depreciation and interest added back. Depreciation is a non-cash charge, and interest is itself part of what is being measured against.
Total debt service adds up every principal repayment and interest payment due on existing and proposed loans during that period. A business applying for a new term loan will typically see the lender calculate this ratio both with and without the new loan added in, comparing the two to see how much cushion would remain once the fresh obligation is added to the mix.
This is also where business loan eligibility starts to get decided in practice, since a lender that sees the ratio fall below its comfort level after adding the new loan will usually scale back the amount on offer rather than reject the application outright.
A Ratio Above One Is the Bare Minimum, Not the Target
A DSCR of exactly one means the business generates just enough cash to cover its debt payments. It has nothing left over if a customer pays late or a cost runs higher than expected. Lenders treat that as a floor, not a comfortable place to sit.
Most banks and NBFCs look for a meaningful buffer above one before they feel confident extending new credit. The exact figure they are comfortable with can change depending on the industry, the loan type, and how long the business has been operating.
A construction contractor with lumpy, milestone-based billing is judged differently than a retailer with steady daily receipts. That applies even if their ratios land on the same number, because the ratio alone does not show how reliably that cash arrives.
What Pulls the Number Down Without Anyone Noticing?
A few things quietly erode this ratio long before an owner notices anything is wrong.
- Carrying several small loans from different lenders instead of consolidating them adds up to a bigger combined debt service figure than most people expect when they total it up.
- A seasonal business that earns most of its income in a few months a year can look fine on an annual average and still fail the ratio if a lender checks a slower quarter in isolation.
- Leaning too heavily on depreciation add-backs to inflate the income side is another common trap, since a lender reviewing the underlying cash flow statement will usually adjust for that anyway.
- And an SME loan applicant who took on a large one-time loan for equipment or expansion sometimes forgets that the ratio is recalculated fresh with every new application, not carried over from whatever it looked like last year.
Lenders Look at More Than One Year
Most credit teams do not rely on a single year’s number in isolation. They typically look at two to three years of financial statements to see whether the ratio has been stable, improving, or sliding, and a business asking for financing tied to a specific project or expansion will often be asked for a projected DSCR based on expected new revenue, not just historical figures.
Some lenders check what the ratio would look like if revenue dropped by a set percentage or interest rates rose. They do this before deciding how much comfort they actually have in the number on paper.
None of this is meant to be intimidating, even though it can feel that way the first time a lender asks for a cash flow statement.
Once a business owner understands that this ratio is really just a cushion check, tracking it becomes a normal part of financial planning. It should not be seen as something that only comes up when a loan application is already on someone else’s desk.